Real Estate Financing Calculator – Calculate Your Property Financing
Property Details
Financing Details
Your estimated financing results are displayed above. This is a non-binding estimate, not financial advice.
Buying a property is one of the most important financial decisions a person can make. In Germany, it’s made more complex by certain conditions, financial planning strategies, and regulations.
This is where our free Real Estate Financing Calculator proves valuable, whether you’re financing a residential property for personal use or a commercial property as an investment. It assesses affordability, provides a cost estimate, and creates repayment plans for both types of financing.
The online Real Estate Financing Calculator helps prospective property buyers understand the long-term financial commitment and identify the various factors that influence it. If you’d also like to keep track of other expenses like taxes or insurance alongside your property, you’ll find suitable calculators for that on Profinanzrechner.
In Germany, several factors influence how real estate financing works, including government regulations, repayment strategies, loan terms, and interest rates.
The Role of a Real Estate Financing Calculator
The Real Estate Financing Calculator plays a central role in determining whether a property purchase is financially feasible, whether it’s residential or commercial. It provides an overview of monthly installments, long-term costs, and the loan term once variables like property price, interest rate, and loan amount are entered. This lets the buyer decide whether they can afford the purchase.
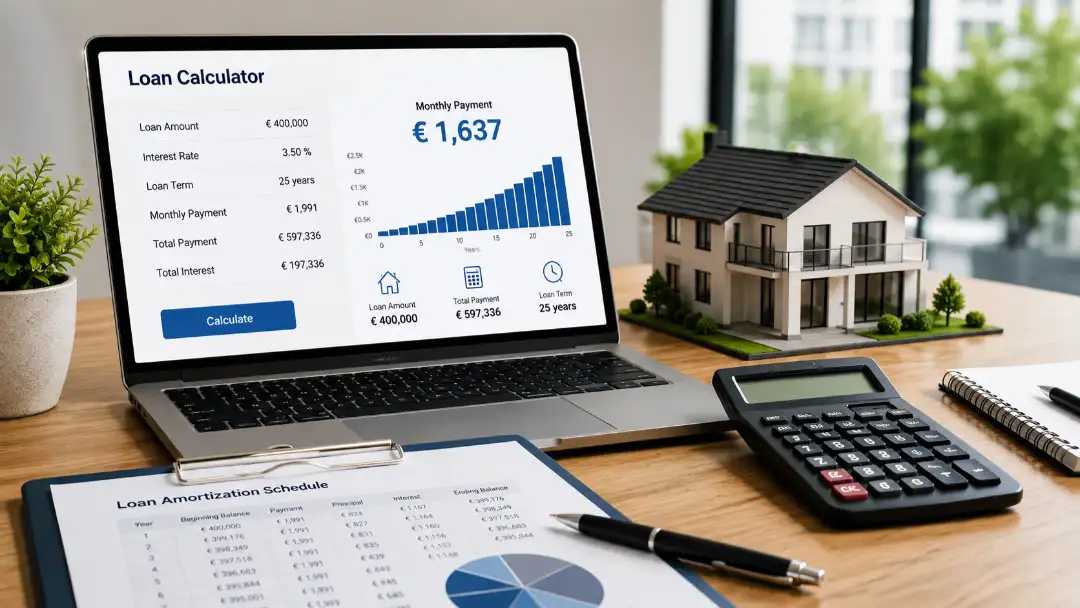
Thanks to the free Real Estate Financing Calculator, users can run through different scenarios without paying a cent. Likewise, a specialized savings bank (Sparkasse) using such a calculator can offer more individualized calculations compared to other banks, based on its specific lending guidelines.
For people who regularly acquire commercial properties, our Real Estate Financing Calculator is an indispensable tool. It helps them understand the costs associated with larger loans and longer repayment periods.
Key Factors That Influence Real Estate Financing in Germany
Buying property, especially in Germany, can be complex due to various influencing factors. Below are some of the most important factors that shape the framework of real estate financing in Germany.
1. Loan Amount and Property Value
The value of a property and the loan amount are directly linked. In Germany, lenders typically grant loans of between 70% and 90% of the purchase price, depending on the buyer’s creditworthiness and financial stability. The interest rate and financing terms for a property depend on the size of the buyer’s down payment.
2. Down Payment (Equity)
Another important factor in real estate financing is equity. A larger down payment lets you benefit from better interest rates and a shorter term, since it reduces the loan-to-value ratio. In Germany, a down payment of at least 20–30% is often recommended to secure favorable terms.
3. Loan-to-Value Ratio
The loan-to-value ratio describes the relationship between the loan amount and the property’s mortgage lending value, and is calculated as follows: (Loan required − equity) × 100 ÷ mortgage lending value. The lower the loan-to-value ratio, the lower the risk for the bank — and generally the more favorable the interest terms offered.
4. Interest Rates
Bei der Berechnung der Gesamtkosten einer Immobilienfinanzierung ist der Zinssatz der wichtigste Kostenfaktor. In Deutschland werden die Zinssätze von der individuellen Risikobewertung, Markttrends und der Politik der Europäischen Zentralbank beeinflusst. Schon geringfügige Zinsschwankungen können erhebliche Auswirkungen auf die Rückzahlungsverpflichtungen haben.
5. Fixed-Interest Period
The fixed-interest period determines how long the agreed interest rate is guaranteed typically 5, 10, 15, or 20 years. A longer fixed-interest period offers more planning security, since the monthly installment stays stable over a longer time. Once the fixed-interest period ends, follow-up financing at the then-current market rate is often required if the loan hasn’t been fully repaid yet.
6. Loan Term
Both the monthly installments and the total cost depend on the loan term. A longer term lowers the monthly installment, but increases the total interest paid. Conversely, shorter terms lead to higher monthly installments but lower total interest.
7. Repayment Rate
How quickly your loan balance decreases depends on the repayment rate. The average repayment rate in Germany is typically between 2% and 3%, but can be adjusted based on financial capacity and income. A higher repayment rate shortens the loan term and reduces interest costs.
8. Income and Financial Stability
Before approving a mortgage, lenders closely examine the borrower’s income, job security, and overall financial situation. Your chances of securing favorable terms are higher if you have a solid, regular income with sufficient disposable income.
9. Creditworthiness (SCHUFA)
SCHUFA is Germany’s credit scoring system. It plays a decisive role in real estate financing. A high SCHUFA score signals a person’s creditworthiness and allows them to obtain loans at lower interest rates.
10. Fixed vs. Variable Interest Rate
In Germany, there are two main types of interest rates: fixed and variable. Variable rates start out low but carry the risk of fluctuation over time. Fixed rates, on the other hand, make long-term planning easier through stable monthly installments that don’t fluctuate.
11. Additional Purchase Costs
In Germany, the purchase price isn’t the only cost involved in buying a property; several additional costs apply, such as:
These additional costs significantly affect the financing needed and can amount to 10–15% of the purchase price.
12. Subsidies and Government Support
The federal government offers various funding programs for family-friendly financing models and energy-efficient housing. Such programs can improve the repayment structure and lower long-term costs. However, not all buyers meet the eligibility requirements.
13. Inflation and Economic Trends
The overall cost of real estate financing and its interest rate are influenced by broader economic conditions such as inflation. Germany offers a comparatively stable and secure environment for property investment. Even so, financing conditions can still fluctuate.
14. Property Location
A property’s location has a significant impact on the loan amount, property value, and long-term appreciation. For example, properties in urban areas tend to achieve high resale value but also require larger loans, whereas in rural areas loans are lower but so is resale value.
15. Residential vs. Commercial Properties
Financing for residential and commercial properties differs in many respects. Residential property loans often involve strict credit checks. For commercial properties, additional factors such as earning potential or business-related risks must also be considered. Our Real Estate Financing Calculator supports you by covering both scenarios.
Example Calculation: Real Estate Financing in Practice
A married couple finds a townhouse for €400,000. Additional costs (real estate transfer tax, notary, land registry) amount to around 10% of the purchase price, or €40,000. They have €120,000 in equity available from an inheritance.
With a 15-year fixed-interest period and an initial repayment rate of 2%, this results in a monthly installment of around €1,573. You can easily recreate this example with your own figures using the Real Estate Financing Calculator.
The Importance of Long-Term Financial Planning
The goal of a real estate financing calculator isn’t just to determine current financial affordability, but also to provide an accurate forecast of long-term commitments. For long-term financial planning, you should build in flexible repayment plans and prepare for possible interest rate increases after the fixed-interest period ends, by ensuring your financial stability can withstand fluctuations in income.
With a well-thought-out financing strategy, you can acquire property without overextending yourself. Use our online Real Estate Financing Calculator to develop such a strategy and compare different repayment scenarios — giving you valuable insight along the way.
Conclusion – Real Estate Financing Calculator
In Germany, real estate financing is a complex process shaped by numerous factors. Understanding these factors is essential for making sound financial decisions and avoiding unwanted risks. The Real Estate Financing Calculator proves indispensable here, offering a clear and precise forecast of long-term costs, repayment schedules, and monthly installments.