Annuity Loan Calculator – Calculate Installment, Repayment, and Interest
Annuity Loan Calculator
Results
Important note: This calculation is for illustrative purposes only and does not constitute a binding offer. We accept no liability for the calculation result. Displayed interest rates are based on your manual inputs.
When taking out a loan for a property or other investment, careful financial planning is essential for long-term stability. In Germany, the annuity loan is one of the most common types of credit — used both in property financing and in classic installment loans. This type of loan is popular with borrowers because it offers high planning security through fixed installments that stay the same throughout the entire term.
With our Annuity Loan Calculator, you can quickly and freely determine your monthly installment, the interest and repayment portions, and the remaining debt. This gives you full clarity for every financing decision. If you have other financial questions beyond financing, you’ll find more suitable calculators on Profinanzrechner.
What Is an Annuity Loan?
An annuity loan is a type of credit where the borrower makes regular fixed installments throughout the entire term, each covering both an interest portion and a repayment portion. Unlike loans with variable installments, the monthly payment on an annuity loan stays constant. While the ratio between the interest and repayment portions shifts over time, the total amount paid per installment remains the same.
At the start of the term, the interest portion of the installment is at its highest, since the remaining debt is still greatest. As repayment progresses, the remaining debt decreases, and with it the interest portion, while the repayment portion continuously increases.
The annuity loan thus offers borrowers a clear, easily plannable model. For a detailed breakdown of your individual financing, use our free Annuity Loan Calculator.
The Role of an Annuity Loan Calculator
The annuity loan calculator plays a central role in financing planning. It helps borrowers balance affordability with long-term stability by providing a clear overview of the repayment schedule.
To get a precise overview of how repayments are distributed over the term, you simply need to enter the loan amount, term, and interest rate. The calculator then automatically determines your monthly installment and the total cost of your loan.
The Annuity Loan Calculator also lets you freely run through different scenarios, such as varying repayment rates or terms.
Calculation Variants: Repayment Rate, Monthly Installment, or Full Repayment
Depending on your financing goal, you can calculate an annuity loan in different ways and choose the repayment strategy that fits your financial situation.
Initial Repayment / Repayment Rate
You specify the desired initial repayment rate (common in property financing, usually between 1% and 4%). The calculator then determines your monthly installment.
Specifying the Monthly Installment
You set the maximum monthly installment you’re willing to pay. The calculator then works out the resulting repayment rate and the remaining debt at the end of the fixed-interest period.
Full Repayment During the Fixed-Interest Period
The loan is fully repaid by the end of the fixed-interest period; in this case, the fixed-interest period matches the entire loan term. This is also known as a full-repayment loan (Volltilgerdarlehen).
Special Repayments: Becoming Debt-Free Faster
Many banks allow annual special repayments — additional payments outside the regular installment that let you reduce your remaining debt faster. Special repayments significantly lower the interest burden over the entire term, since they directly reduce the remaining debt on which future interest is calculated. With our calculator, you can see directly how an annual special repayment affects your total costs.
Nominal Interest Rate and Effective Annual Interest Rate
When searching for a loan, you’ll come across two different interest figures: the nominal interest rate (Sollzins) is the pure loan interest rate excluding additional costs. The effective annual interest rate (effektiver Jahreszins) also factors in all costs and payment terms associated with the loan, making it the more meaningful figure for comparing different loan offers.
Advantages of an Annuity Loan
Disadvantages of an Annuity Loan
Who Is an Annuity Loan Suitable For?
An annuity loan is particularly suitable for the following groups:
Budget-conscious borrowers:
People who plan their monthly expenses carefully and prefer fixed, predictable installments.
Property buyers:
The annuity loan is the most common form of financing for buying or building a property in Germany.
Security-oriented borrowers:
Anyone who prefers stability over flexibility benefits from the fixed installment structure.
First-time buyers:
The fixed, predictable monthly installment offers a high degree of security, especially for a first major purchase.
People who want to avoid interest rate risk:
Anyone wanting protection against rising interest rates during the term benefits from the fixed-interest period.
Factors That Influence an Annuity Loan
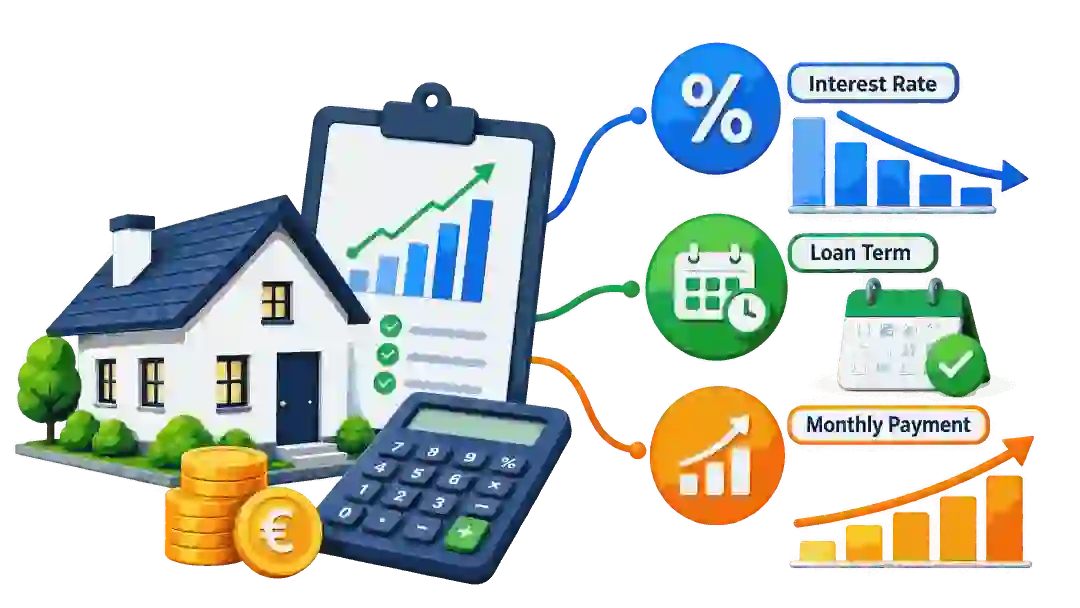
The cost and course of an annuity loan are determined by several factors that affect both the monthly installment and the total interest cost.
Interest rate
The interest rate is one of the most important factors influencing the total cost of an annuity loan. A lower interest rate noticeably reduces the overall burden.
Fixed-interest period
A longer fixed-interest period offers more planning security but often comes with a somewhat higher interest rate. A shorter fixed-interest period can be cheaper but carries a higher risk when it comes to follow-up financing.
Initial repayment rate
A higher initial repayment rate leads to a higher monthly installment but lowers the total interest cost and significantly shortens the term.
Example Calculation: Calculating an Annuity Loan
Suppose you take out a loan of €200,000 with a nominal interest rate of 3.5% p.a. and an initial repayment rate of 2%.
As the term progresses, the interest portion continuously decreases, while the repayment portion steadily grows as the installment stays the same. Our calculator shows you this exact progression in the full amortization schedule.
Conclusion – Annuity Loan Calculator
The annuity loan is regarded in Germany as one of the most stable and popular financing models, whether for private individuals, families, or property buyers. It offers predictability and security but also comes with limitations on flexibility. Before signing a contract, borrowers should therefore carefully check whether the chosen fixed-interest period and repayment structure fit their individual financial situation.
Our Annuity Loan Calculator supports you in this by factoring in the term, interest rate, repayment rate, and special repayments, giving you a solid basis for your decision.